Showing posts with label Energy crisis. Show all posts

Wednesday, December 27, 2017

THE U.S. SHALE OIL INDUSTRY: Swindling & Stealing Energy To Stay Alive

SRSrocco


By the SRSrocco Report,


While the U.S. Shale Energy Industry continues to borrow money to produce uneconomical oil and gas, there is another important phenomenon that is not understood by the analyst community.  The critical factor overlooked by the media is the fact that the U.S. shale industry is swindling and stealing energy from other areas to stay alive.  Let me explain.


First, let"s take a look at some interesting graphs done by the Bloomberg Gadfly.  The first chart below shows how the U.S. shale industry continues to burn through investor cash regardless of $100 or $50 oil prices:


The chart above shows the negative free cash flow for 33 shale-weighted E&P companies.  Even at $100 oil prices in 2012 and 2013, these companies spent more money producing shale energy in the top four U.S. shale fields than they made from operations.  While costs to produce shale oil and gas came down in 2015 and 2016 (due to lower energy input prices), these companies still spent more money than they made.  As we can see, the Permian basin (in black) gets the first place award for losing the most money in the group.


Now, burning through investor money to produce low-quality, subpar oil is only part of the story.  The shale energy companies utilized another tactic to bring in additional funds from the POOR SLOBS in the retail investment community... it"s called equity issuance.  This next chart reveals the annual equity issuance by the U.S. E&P companies:


According to the information in the chart, the U.S. E&P companies will have raised over $100 billion between 2012 and 2017 by issuing new stock to investors.  If we add up the funds borrowed by the U.S. E&P companies (negative free cash flow), plus the stock issuance, we have the following chart:


Thus, the U.S. E&P companies tapped into an additional $212 billion worth of funding over the last six years to produce uneconomical shale oil and gas.  Now, this chart is an approximation based on the negative free cash flow (RED color) from the four top U.S. shale fields and the shale equity issuance (OLIVE color).  So, how much money would these U.S. E&P companies need to make to pay back these funds?


Good question.  If we assume that the U.S. shale oil companies will be able to produce another 10 billion barrels of oil, they would need to make $21 a barrel profit to pay back that $212 billion.  However, they haven"t made any profits in at least the past six years, so why would they make any profits in the next six years?


Okay, now that we understand that the U.S. shale industry has been burning through cash and issuing stock to continue an unprofitable business model, let"s take it a step further.  If we understand that the U.S. shale energy industry is not making enough money from producing the oil and gas, then it also means that it takes more energy to produce it then we are getting from it.  Sounds strange... but true.


We must remember, investors, furnishing U.S. shale energy companies with funds are another way of providing ENERGY.  These U.S. shale energy companies are taking that extra $212 billion (2012-2017) and burning the energy equivalent to produce their oil and gas.  For example, it takes a lot more water to frack oil and gas wells.  To transport the water, we either do it by truck or by pipeline.  While this extra water usage is a Dollar Cost to the shale energy industry, it is really an ENERGY COST.  Think about all the energy it took to either transport the water by truck, or the energy it took to make the pipelines, install them and the energy to pump the water.


Moreover, if we add up all of the additional costs to produce U.S. shale oil and gas, the majority of it comes from burning energy, in one form or another.  Again, investor funds translate to burning energy.  Thus, the U.S. shale industry needs more energy to produce the oil and gas than we get from it in the first place.


Unfortunately, investors don"t see it this way because they do not realize they will never receive their investment back.  It was spent and burned years ago to continue the Great U.S. Shale Energy Ponzi Scheme.


Let me put it in another way.  The U.S. and world economies are based on burning energy.  When we burn energy, we create economic activity and hopefully growth.  If the U.S. shale energy industry needed $212 billion more to produce the oil than they made from operations, then it means it burned more energy than it sent to the market.  Do you see that now??


So, the U.S. shale energy industry is STEALING & SWINDLING energy wherever it can to stay alive.  This is the perfect example of the Falling EROI (Energy Returned On Investment) forcing an industry to CANNABLIZE itself (and the public) to keep from going bankrupt.


Lastly, as time goes by the U.S. shale energy industry will behave like a BLACK HOLE, by sucking more and more energy in to produce even lower and lower quality oil and gas.  At some point, the shale energy industry will collapse upon itself leaving one hell of a mess behind.  While it"s hard to predict the timing of the event, it will likely occur within the next 2-5 years.


Check back for new articles and updates at the SRSrocco Report. 

Tuesday, December 19, 2017

OPEC vs IEA: Who"s Right On Oil Prices?

Authored by Nick Cunningham via OilPrice.com,


Last week, the International Energy Agency made a lot of OPEC brows furrow when it warned that 2018 may not be a very happy new year for the cartel.


U.S. shale supply, the IEA said in its December Oil Market Report, is set to grow more than OPEC has estimated and this could be the undoing of the production cut that boosted prices this year.


OPEC, for its part, has insisted that U.S. shale production won’t grow as much as the IEA says, baffling some observers who now wonder who they should believe. But let’s put it another way: If the coach of a football team tells you that his team will win the cup because they’re the best, but the football association has estimated that the team is not the best one in the league, who would you believe?


OPEC has a history of underestimating U.S. shale. This underestimation led to the glut that sank prices in 2014. Now it stands to reason that the cartel is more cautious in its estimates of U.S shale oil developments, but this caution does not necessarily have to be reflected in comments. Let’s not forget that comments from OPEC officials—whether or not grounded in facts—have had a direct and immediate effect on prices from events such as the shutdown of the Forties pipeline network last week.


So, it would make sense to lean more towards what the IEA says, and it says that non-OPEC supply next year will probably rise by 1.6 million bpd—a 200,000 bpd upward revision on the previous OMR. U.S. shale production alone will, according to IEA’s latest estimate, grow by 870,000 bpd in 2018. Meanwhile, demand will rise by 1.3 million barrels daily next year, hinting at another glut in the making. 


Now, OPEC’s last forecast is that non-OPEC supply next year will rise by just 990,000 bpd next year to 58.81 million bpd, although the group does caution that any non-OPEC supply growth forecast involves considerable uncertainties regarding U.S. shale production growth. For the U.S. specifically, OPEC forecasts a 1.05-million-barrel daily supply growth next year, which will be partially offset by declines in producers such as Russia, China, and Mexico, among others.


That’s quite a discrepancy between IEA and OPEC figures, but it’s not the only one. The two more notably disagree on when the glut will be over. IEA is skeptical about it disappearing before the end of next year, while OPEC is upbeat, believing the market will return to balance in the second half of 2018 as demand growth accelerates. 


Sometimes OPEC’s forecasts sound like developments that the cartel can will into existence, and this market rebalancing forecast is one of these cases. It’s true that some OPEC members have been very diligent in their compliance to the lower production quotas. Others not so much, so those from the first group have actually cut more than they agreed to in order to compensate for the non-compliant ones.


Can the overachievers continue doing this to ensure the forecast materializes? They can, but they can’t do anything about U.S. shale, and it’s uncertain whether Russia will stay in the agreement after the end of June: Moscow has indicated it would rather quit as soon as politely possible. OPEC also has another problem that’s been there since the original deal, but recently has been garnering more attention. With oil prices higher, how long until one or more OPEC members decide to drop the deal and cash in on the price increase?


Friday, December 15, 2017

The "Unknown Unknowns" That Threaten U.S. Shale

Authored by Tsvetana Paraskova via OilPrice.com,


Three years after the oil price crash, the U.S. shale patch is on its second growth phase and is expected to continue to increase its production, at least through the next five years.


The global oil markets have become increasingly dependent on U.S. tight oil supply - and the oil industry is still coming to grips with this new reality, Simon Flowers, Chairman and Chief Analyst at Wood Mackenzie, wrote in a recent article.


Current projections put the Permian on the forefront of the United States’ ability to deliver increased tight oil supply to the global markets. However, forecasts for the shale patch are as dynamic as production and drilling rates are. And some ‘known unknowns’ have been surfacing such as higher gas-to-oil ratios in some wells, and the parent/child wells issue, Flowers says.


Wood Mackenzie said last month that signs had started to show that intensified drilling in the Permian doesn’t deliver commensurate volumes of oil. Although WoodMac thinks that such setbacks could just be growing pains and Permian drillers could indeed ‘change the laws of physics’, it had warned three months ago that drillers might soon start to test the region’s geological limits. If exploration and production companies can’t overcome the geological constraints with tech breakthroughs, Permian production could peak in 2021, putting more than 1.5 million bpd of future production in question and potentially significantly influencing oil prices, WoodMac said in September.


In his December article, WoodMac’s Flowers included this observation in the Permian’s ‘known unknowns’:


“Growth might also be constrained by shareholders demanding that independents rein back from volume-driven targets.”


Those ‘known unknowns’ serve as a warning: the oil market can’t be complacent and just assume that the Permian boom will deliver as expected, according to Flowers. The Wolfcamp may be the star of the Permian, WoodMac says, but “there are more than likely ‘unknown unknowns’ out there too. And if there are, there’s not another Permian ready to step in; and conventional options will take time to crank into action.”


The Eagle Ford and the Bakken combined represent nearly half of the current U.S. tight oil production, according to Wood Mackenzie, which is expressing new doubts that those two plays could offer long-term commercial drilling inventory as operators move out beyond the sweet spots. Therefore, the analysts downgraded the growth rates for both plays from the mid-2020s, but have significantly upgraded the Permian growth pace, especially for the Wolfcamp basin.


If the Permian turns out to have ‘unknown unknowns’ alongside the ‘known unknowns’, the U.S. shale patch may not deliver as expected.


Currently, WoodMac’s supply/demand balance forecasts show that the U.S. and OPEC will “do battle for contestable demand that will climb to over 5 million b/d by 2024.”


The analysts believe that U.S. shale will take the lion’s share of that demand—90 percent—as its production will double to 9.6 million bpd by 2024 from 4.9 million bpd in 2017, while OPEC will be left with meeting less than 1 million bpd of that additional demand.


Three years after the oil price crash, the most unexpected outcomes in the global oil market are the second wave of U.S. shale growth, OPEC’s “zealous adherence” to the cuts, and the resilience of some non-OPEC non-U.S. producers, WoodMac says.


While Mexico, China, and Africa as a whole have been “heavy casualties” of the lower-for-longer oil prices, Russia, Canada, and the North Sea have surprised on the positive side by adapting remarkably well to the low oil prices. Russia is the “poster child” of this resilience. Canada is also doing well with Duvernay liquids where breakevens are competitive with U.S. plays, and with better uptime from oil sands projects. The North Sea has also been a positive surprise, with the UK leading the way with aggressive cost cuts that have helped to raise oil production, WoodMac says.


Still, U.S. tight oil, especially the Permian, will be the main growth story over the medium term, but ‘unknown unknowns’ may be lurking out there and could restrain the pace of that growth.


Monday, November 27, 2017

OPEC, Russia Said To Announce Oil Pact Extension On Nov 30

Authored by Tsvetana Paraskova via OilPrice.com,


Saudi Arabia and Russia have agreed that OPEC and non-OPEC allies should announce an extension of the cuts at the highly-anticipated meeting in Vienna on November 30, Bloomberg reported on Friday, quoting people involved in the talks.


Recent OPEC/non-OPEC oil pact chatter had it that Saudi Arabia was pushing for an announcement of the cuts extension next week in Vienna, while Russia was more hesitant about telling the market on November 30 how the participants in the deal would act. Russia appeared to be stalling and playing for an announcement to be issued closer to the current expiration deadline of the deal, March 2018.


According to Bloomberg’s sources, now Russia and Saudi Arabia have agreed on the need to announce some sort of a deal next week, but Russia has insisted on additional phrasing in the extension deal that would link the size of the cuts to the state of the oil market.


While OPEC and Russia have agreed on a general framework, discussions are ongoing as to how OPEC could meet Russia’s demands, including how to include a link between the size of the cuts and the state of the rebalancing of the oil market. There are also discussions about including an option to review the pact again in early 2018, including calling a new meeting, according to Bloomberg’s sources.


As of last week, not all Russian oil companies were on board with extending the cuts, and they were said to have discussed a six-month extension with Energy Minister Alexander Novak.


Novak, for his part, said on Friday in a television interview posted on the energy ministry’s website that some 50 percent of the global oil oversupply had been erased and Brent prices had risen to an “acceptable enough” level of more than $60 a barrel.


Nevertheless, the oil market is not yet balanced and the pact needs to be extended, Novak said, adding that Russia supports an extension, and various options are being discussed.


Details will be discussed at the Vienna meeting next week, he noted. 


Sunday, November 19, 2017

The Coming Economic Downturn In Canada

Authored by Deb Shaw via MarketsNow.com,


  • Canadian GDP growth has outperformed this year, helping the Canadian dollar

  • As GDP growth slows and the Bank of Canada turns neutral, catalysts turning negative

  • Crude oil and real estate look set for a downturn, with negative implications for the currency


Given its natural resource-based economy, Canada is a boom and bust kind of place. This year, the country has enjoyed a significant boom. Thanks to a government stimulus program, rising corporate capital expenditures and consumer spending, Canada’s GDP growth has been nothing short of spectacular in 2017. According to Statistics Canada, the latest reading for year-over-year GDP growth is a healthy 3.5% (as of August 2017). While this is stronger than all major developed countries, growth is decelerating from its most recent peak in May 2017 (when GDP growth was an astounding 4.7%). A visual overview of historical GDP growth is shown below for reference:


Turning a corner: Canadian growth comes back down to earth


11-17-2017 CAD GDP growth


Source: Statistics Canada


Following the crude oil bust in the second quarter of 2014, Canadian growth rates cratered. While the country avoided a technical recession, the economic outlook was poor until early 2016. After crude oil returned to a bull market in the first quarter of 2016, the fortunes of the country turned. Given limited growth in 2015, the economy had no problem delivering 2%+ year-over-year growth rates in 2016. As a substantial stimulus program ramped up government spending in 2017, growth rates have continued to accelerate this year.


Storm clouds on the horizon: crude oil and real estate


While Canada has delivered exceptional growth in the last two years, the future outlook is much more challenging. Beyond the issue of base effects (mathematically, year-over-year GDP growth will be much tougher next year), key sectors including the oil & gas industry and Canadian real estate look ripe for a downturn.


Crude bull market intact today, but at risk in 2018


As WTI crude strengthens beyond $55, crude oil is clearly in a bull market today. Looking at figures from the International Energy Agency, global demand growth continues to run ahead of supply growth. Thus the ongoing bull market is supported by fundamentals. Thanks to the impact of hurricanes and infrastructure bottlenecks in 2017, US shale hasn’t entirely fulfilled its role as the global ‘swing producer’ this year. The dynamics of supply growth versus demand growth are shown below:


Who invited American shale? US supply ruins the crude oil party


10-13-2017 crude oil supply demand


Source: International Energy Agency, forward OPEC supply estimates via US EIA


Unfortunately, the status quo looks set to change as US supply returns with a vengeance. According to estimates from the IEA, supply growth will outstrip demand growth in the first quarter of 2018. Digging deeper into supply estimates, US shale is once again to blame. Our view is that this changing dynamic will lead to a new bear market in crude oil. Looking back at recent history, crude prices formed a long-term top in the second quarter of 2014 once supply growth overtook demand. Similarly, crude prices bottomed in the first quarter of 2016 once supply growth fell below demand in early 2016. Given Canada"s dependence on crude oil exports, a bear market for the commodity is likely to result in a weaker currency.


As China enters its latest real estate downturn, Canada not far behind


While Canadian real estate has enjoyed a great year, the future outlook is much tougher. Similar to its peers in Australia and New Zealand, Canadian real estate prices tend to lag real estate prices in China. This is both because Canada’s economy is deeply intertwined with China, and because the country is a big destination for overseas investment from China. While overseas investors make up a relatively small portion of buyers (around 5% according to government estimates), they serve an important role by acting as the marginal buyer for prime property. A comparison of new house prices in China versus Canada is shown below for reference:


Canadian real estate boom set to run out of steam


11-17-2017 China Canada real estate


Source: Statistics Canada, China National Bureau of Statistics


As Chinese new house prices accelerated significantly in early 2015, Canadian real estate prices followed in 2016. As the Chinese market is now decelerating, negative growth appears to be on the horizon. In March 2015, Chinese house price growth bottomed at -6.1%. While the Canadian bull market continues for now (September new house prices registered at 3.8%), a downturn is likely over the next 6-12 months. As real estate makes up 13% of Canadian GDP, a significant decline in the fortunes of the industry are likely to spill over to the broader economy.


Implications for the Canadian dollar


At the beginning of the year, the Canadian dollar enjoyed a wide number of bullish catalysts including accelerating GDP growth, rising rate hike expectations, a relatively strong crude oil market and speculator sentiment that was at a bearish extreme. These catalysts, and the Bank of Canada’s actions in particular, helped the currency strengthen until late September.


Today, almost every factor that drives the Canadian dollar is working against it. Future GDP growth rates are set to keep decelerating. Looking at the Bank of Canada, its outlook for future rate hikes is now “cautious”. This is a big change from its hawkish tilt earlier this year. While speculator sentiment is no longer at bullish extremes, waning interest in the Canadian dollar is weighing on the currency. The ongoing NAFTA negotiations are another source of potential political risk. Finally, an impending downturn for both crude oil and Canadian real estate further worsen the picture. Thus, our longer term outlook on the Canadian dollar is bearish.


Thursday, November 9, 2017

Satellite Images Reveal Saudis May Be Lying How Much Oil They Have In Storage

A little over a year ago, specialized satellite imaging company Orbital Insight which uses its proprietary imaging and algorithms to track above-ground oil storage, confirmed something we had alleged earlier in the year: that China was vastly under-representing the amount of oil it had stored in its Strategic Petroleum Reserve (with significant implications for prices). As we said last September "according to Orbital Insight, China had not only misrepresented how much oil it has stored, it has done so at a massive scale, with the real number dwarfing even JPM own estimate: the real amount of Chinese oil in storage, according to Orbital, was a whopping 600 million barrels as of May" an amount nearly 3 times greater than the official, at the time, number of 234 million barrels.


The resultant doubt about China"s true purchasing capacity was one of the several factors that led to the subsequent swoon in oil prices which OPEC was unable to overcome until nearly a year later, when the market became increasingly confident that the OPEC strategy of eliminating excess inventory, was working and pushed the price of WTI and Brent to two year highs, above $57 and $63 respectively.


That confidence may not last, however, and the reason may be the same one as last year: Orbital Insights.


As the FT"s David Sheppard writes, "while the oil market’s attention has been gripped this week by the corruption purge in Saudi Arabia and its tensions with Iran, from miles above the earth’s crust one company is highlighting a different kind of intrigue."  He is, of course, referring to Orbital Insight, whose analysis of Saudi crude inventories in recent months has thrown up an "interesting anomaly."


One can call it an "anomaly", but a better explanation of what the company has done is to catch the Saudi kingdom in lying about its inventories. Here is the official narrative:


The kingdom, which has led Opec and Russia in co-ordinated output cuts since January, has for months been reporting to official agencies that its oil held in storage has been falling, which alongside lower production has been one factor that has helped propel Brent crude oil back above $60 a barrel.


There is just one problem: it"s a lie: "Orbital’s analysis of satellite imagery suggests that Saudi Arabia’s above-ground tanks — whose floating roofs allow them to see when oil inventories are rising or falling by measuring shadows cast across the top of the tanks — have seen no real change in the past 18 months."


This, Orbital says, is interesting because before early 2016, movements in above-ground storage closely tracked the trend in Saudi’s official numbers submitted to the Joint Organisations Data Initiative that are crucial for traders and analysts trying to get a grip of the near 100m barrel-a-day oil market.


In other words, the Saudis did not always lie about their inventory - it"s only recently that the nation decided to "pull a China" and misrepresent its true crude inventories... in fact, it only started as OPEC began aggressively jawboning the market to send the price of oil higher in the buildup to the Nov 2016 Vienna production cut agreement. In the process, OPEC"s most important member would do anything to give the fake impression there is more demand, and thus less oil in storage, than there really was.


How much? Here"s the FT"s punchline: "While Saudi Arabia has reported to Jodi that its oil stocks have declined by about 70m barrels since early 2016, the Orbital analysis suggests the above-ground tanks have actually seen inventories rise marginally over the same period."


If confirmed, Orbital"s startling allegation would imply that for much of the past two years, OPEC has been actively engaged in doing what it does best: cheating, not only the market, but also other cartel members, because if Saudi peers found out that Saudi Arabia was quietly warehousing tens of millions of barrels in excess oil to give the false impression of high demand, then everyone else would start doing it. Come to think of it, maybe they are...


Still, as the FT and Orbital point out, there are a few caveats.  For one, Saudi Arabia’s official storage numbers include oil held overseas, in key regional hubs. It also covers line-fill for pipelines and underground tanks that cannot be monitored by eyes in the sky.  These factors may account for why the numbers no longer seem to match up — though they do raise other questions. Orbital says that changes in inventory levels in above-ground domestic storage tanks are normally noticeable normally first as they are easiest to access. Saudi’s Jodi numbers and what Orbital can see through its algorithmic analysis of the satellite imagery had previously tracked each other closely.


“The floating tank data is the part that we think is most indicative of short-term changes in storage,” said James Crawford, chief executive of Orbital Insight. “The big question is why that no longer jives with the government data that shows a pretty big drop."


There may be another explanation and it has to do with keeping higher oil storage levels at home than abroad. As the FT explains, "the most intriguing suggestion for the shift is more strategic: Riyadh’s own concerns about rising tensions with its neighbours."


“[The] reason for no real deep stock draw in [the] kingdom will be mainly security related,” said Cyril Widdershoven, who runs the Verocy consultancy.


That suggests, he said, that Saudi Arabia is concerned enough about its deteriorating relationship with Iran, and to a lesser degree Qatar, to keep higher oil stocks at home in case of any disruption.


To be sure, with Crown Prince Mohammed bin Salman saying this week that Iran’s support for Houthi fighters in Yemen, and the provision to them of missiles capable of striking deep into the kingdom, constitutes an act of war, "it is certainly an intriguing theory", one which Shepperd writes that "at times of heightened tension between two of Opec’s biggest producers it is one the market may start tracking closely."


And while there is no definitive explanation for the inventory discrepnacy observed by Orbital, what makes this mystery especially intriguing is how polar opposite the two most likely explanation are in terms of oil prices: either Saudi Arabia is covering up the lack of demand and warehousing excess oil, which will eventually send oil prices sliding, or if the "security-related" explanation is accurate, then Saudi Arabia is indeed preparing for war with Iran, which once the shooting begins will send the price of oil into the stratosphere.


Sunday, October 15, 2017

The Death Of Petrodollars & The Coming Renaissance Of Macro Investing

Authored by John Curran via Barrons,


The petrodollar system is being undermined by exponential growth in technology and shifting geopolitics. What comes next is a paradigm shift...


In the summer of 1974, Treasury Secretary William Simon traveled to Saudi Arabia and secretly struck a momentous deal with the kingdom. The U.S. agreed to purchase oil from Saudi Arabia, provide weapons, and in essence guarantee the preservation of Saudi oil wells, the monarchy, and the sovereignty of the kingdom. In return, the kingdom agreed to invest the dollar proceeds of its oil sales in U.S. Treasuries, basically financing America’s future federal expenditures.


Soon, other members of the Organization of Petroleum Exporting Countries followed suit, and the U.S. dollar became the standard by which oil was to be traded internationally. For Saudi Arabia, the deal made perfect sense, not only by protecting the regime but also by providing a safe, liquid market in which to invest its enormous oil-sale proceeds, known as petrodollars. The U.S. benefited, as well, by neutralizing oil as an economic weapon. The agreement enabled the U.S. to print dollars with little adverse effect on interest rates, thereby facilitating consistent U.S. economic growth over the subsequent decades.


An important consequence was that oil-importing nations would be required to hold large amounts of U.S. dollars in reserve in order to purchase oil, underpinning dollar demand. This essentially guaranteed a strong dollar and low U.S. interest rates for a generation.


[ZH: Still, the underlying concept of how Petrodollar recycling, or as some call it, petrocurrency mercantilism works, leaves some confusion. So in order to alleviate that, here courtesy of Cult State, is a quick and simple primer that should hopefully answer all questions. From CultState:


So what is petrocurrency mercantilism?


It’s when a national bank and an energy producer collude to generate artificial demand for a currency at the expense of the purchasing power of other currencies.


The flowchart below shows how it all works.


Given this backdrop, one can better understand many subsequent U.S. foreign-policy moves involving the Middle East and other oil-producing regions.


Recent developments in technology and geopolitics, however, have already ignited a process to bring an end to the financial system predicated on petrodollars, which will have a profound impact on global financial markets. The 40-year equilibrium of this system is being dismantled by the exponential growth of technology, which will have a bearish impact on both supply and demand of petroleum. Moreover, the system no longer is in the best interest of key participants in the global oil trade. These developments have begun to exert influence on financial markets and will only grow over time. The upheaval of the petrodollar recycling system will trigger a resurgence of volatility and new price trends, which will lead to a renaissance in macro investing.


Let’s examine these developments in more detail.


First, TECHNOLOGY is affecting the energy markets dramatically, and this impact is growing exponentially. The pattern-seeking human mind is built for an observable linear universe, but has cognitive difficulty recognizing and understanding the impact of exponential growth.


Paralleling Moore’s Law, the current growth rate of new technologies roughly doubles every two years. In the transportation sector, the global penetration rate of electric vehicles, or EVs, was 1% at the end of 2016 and is now probably about 1.5%. However, a doubling every two years of this level of usage should lead to an automobile market that primarily consists of EVs in approximately 12 years, reducing gasoline demand and international oil revenue to a degree that today would seem unfathomable to the linear-thinking mind. Yes, the world is changing—rapidly.


Alternative energy sources (solar power, wind, and such) also are well into their exponential growth curves, and are even ahead of EVs in this regard. Based on growth curves of other recent technologies, and due to similar growth rates in battery technology and pricing, it is likely that solar power will supplant petroleum in a vast portion of nontransportation sectors in about a decade. Albert Einstein is rumored to have described compound interest (another form of exponential growth) as the most powerful force in the universe. This is real change.


The growth of U.S. oil production due to new technologies such as hydraulic fracturing and horizontal drilling has both reduced the U.S. need for foreign sources of oil and led to lower global oil prices. With the U.S. economy more self-reliant for its oil consumption, reduced purchases of foreign oil have led to a drop in the revenues of oil-producing nations and by extension, lower international demand for Treasuries and U.S. dollars.


ANOTHER MAJOR SECULAR CHANGE that is under way in the oil market comes from the geopolitical arena. China, now the world’s largest importer of oil, is no longer comfortable purchasing oil in a currency over which it has no control, and has taken the following steps that allow it to circumvent the use of the U.S. dollar:


  • China has agreed with Russia to purchase Russian oil and natural gas in yuan.

  • As an example of China’s newfound power to influence oil exporters, China has persuaded Angola (the world’s second-largest oil exporter to China) to accept the yuan as legal tender, evidence of efforts made by Beijing to speed up internationalization of the yuan. The incredible growth rates of the Chinese economy and its thirst for oil have endowed it with tremendous negotiating strength that has led, and will lead, other countries to cater to China’s needs at the expense of their historical client, the U.S.

  • China is set to launch an oil exchange by the end of the year that is to be settled in yuan. Note that in conjunction with the existing Shanghai Gold Exchange, also denominated in yuan, any country will now be able to trade and hedge oil, circumventing U.S. dollar transactions, with the flexibility to take payment in yuan or gold, or exchange gold into any global currency.

  • As China further forges relationships through its One Belt, One Road initiative, it will surely pull other exporters into its orbit to secure a reliable flow of supplies from multiple sources, while pressuring the terms of the trade to exclude the U.S. dollar.

The world’s second-largest oil exporter, Russia, is currently under sanctions imposed by the U.S. and European Union, and has made clear moves toward circumventing the dollar in oil and international trade. In addition to agreeing to sell oil and natural gas to China in exchange for yuan, Russia recently announced that all financial transactions conducted in Russian seaports will now be made in rubles, replacing dollars, according to Russian state news outlet RT. Clearly, there is a concerted effort from the East to reset the economic world order.


ALL OF THESE DEVELOPMENTS leave global financial markets vulnerable to a paradigm shift that has recently begun. In meetings with fund managers, asset allocators, and analysts, I have found a virtually universal view that macro investing—investing based on global macroeconomic and political, not security-specific trends—is dead, fueled by investor money exiting the space due to poor returns and historically high fees in relation to performance. This is what traders refer to as capitulation. It occurs when most market participants can’t take advantage of a promising opportunity due to losses, lack of dry powder, or a psychological inability to proceed because of recency bias.


A current generational low in volatility across a wide spectrum of asset classes is another indicator that the market doesn’t see a paradigm shift coming. This suggests that current volatility is expressing a full discounting of stale fundamental inputs and not adequately pricing in the potential of likely disruptive events.


THE FEDERAL RESERVE is now in the beginning stages of a shift toward “normalization,” which will lead to diminished support for the U.S. Treasury market. The Fed’s total assets stand at approximately $4.5 trillion, or five times what they were prior to the financial crisis of 2008-09. The goal of the Fed is to “unwind” this enormous balance sheet with minimal market disruption. This is a high-wire act a thousand feet in the air without a safety net or prior practice. Additionally, at some not-so-distant future date, the U.S. will need to finance enormous and growing entitlement programs, and our historical international sources for that financing will no longer be willing to support us in that endeavor.


The market participants with whom I met theoretically could have the ability to accept cognitively the points made in this article. But the accumulation of many small losses in a low-volatility and generally trendless market has robbed them of confidence and the psychological balance to embrace any new paradigm proactively. They are frozen with fear that the lower- return profile of recent years is permanent—ironic in an industry that is paid to capture price changes in a cyclical world.


One market legend with whom I spoke suggested he wouldn’t have had the success he enjoyed in his career had he begun in the past decade. Whether or not this might be true, it doesn’t mean that recent lower returns are to be extrapolated into the future, especially when these subpar returns occurred during the quantitative-easing era, a period that is an anomaly.


I have been fortunate to ride substantial bets on big trends, earning high risk-adjusted returns using time-tested techniques for exploiting these trends. Additionally, I have had the luxury of not participating actively full-time in macro investing during this difficult period. Both factors might give me perspective. I regard this as an extraordinarily opportune moment for those able to shed timeworn, archaic assumptions of market behavior and boldly return to the roots of macro investing.


The opportunity is reminiscent of the story told by Stanley Druckenmiller, who was promoted early in his investment career to head equity research at a time when his co-workers had vastly more experience than he did. His director of investments informed him that his promotion owed to the same reason they send 18-year-olds to war; they are too dumb to know not to charge. The “winners” under the paradigm now unfolding will be market participants able to disregard stale, anomalous concepts, and charge.


RELATEDLY, THERE IS a running debate as to whether trend-following is a dying strategy. There is plenty of anecdotal evidence that short-term and mean-reversion trading is more in vogue in today’s markets (think quant funds and “prop” shops). Additionally, the popularity of passive investing signals an unwillingness to invest in “idea generation,” or alpha. These developments represent a full capitulation of trend following and macro trading.


Ironically, many market players who wrongly anticipated a turn in recent years to a more positive environment for macro and trend-following are throwing in the towel. The key difference is that now there is a clear catalyst to trigger the start of the pendulum swinging back to a fertile macro/trend-following trading environment.


As my mentor, Bruce Kovner [the founder of Caxton Associates] used to say, “Nobody rings a bell at key turning points.” The ability to properly anticipate change is predicated upon detached analysis of fundamental information, applying that information to imagine a plausible world different from today’s, understanding how new data points fit (or don’t fit) into that world, and adjusting accordingly. Ideally, this process leads to an “aha!” moment, and the idea crystallizes into a clear vision. The thesis proposed here is one such vision.

Wednesday, October 11, 2017

OPEC To Take Drastic Action Despite Shale Slowdown

Authored by Nick Cunningham via OilPrice.com,


WTI recently dipped below $50 per barrel for the first time in a month, erasing the strong September rally. It’s no coincidence that after two weeks of price declines, OPEC has tried to talk up the oil market again, hinting that more drastic action could be forthcoming.


Echoing the world’s top central bankers, OPEC’s Secretary General said that the oil cartel might need to take “extraordinary” measures to balance the oil market next year. “There is a growing consensus that, number one, the re-balancing process is underway,” OPEC’s Mohammad Barkindo told reporters on Sunday in New Delhi. “Number two, to sustain this into next year, some extraordinary measures may have to be taken in order to restore this stability on a sustainable basis going forward.”


As always, OPEC is vague on the specifics, but the working assumption is that the group will agree to an extension of the cuts until at least mid-2018, or perhaps even as late as through the end of the year. There’s been some discussion about deeper production cuts, but there aren’t a ton of analysts who see OPEC going that far, despite Barkindo’s cryptic language.


Meanwhile, Saudi Arabia engaged in a bit of its own psy-ops with the oil market on Monday, saying that it was taking “unprecedented” steps to cut its oil exports. Saudi Aramco said it would lower exports by 560,000 bpd next month, “the deepest customer allocation cuts in its history.”


The comments are consistent with the country’s longstanding pattern of trying to jawbone the market when it wants higher prices. Based on Monday’s activity, the effort didn’t work.


“The fact that we did not get any significant strength from the Saudi news is rather disheartening for the bulls,” Stephen Schork, an analyst and author of the Schork Report, told the WSJ. “The market is very skeptical of this.”


Of course, real cuts to oil exports will be felt if they are carried out, but after a few years of getting jerked around by every utterance from OPEC, the markets want to see proof in the pudding. Aggressive rhetoric no longer moves the market the way it did a year ago, so we’ll have to just wait and see what OPEC does at its November meeting.


“With rising production levels and no definitive word from OPEC and the Russians that they are going to extend the cut or deepen it, the rally seems to have lost its momentum,” Gene McGillian, a market research manager at Tradition Energy, said in a Bloomberg interview.


That reaction seemed to be widespread on Monday. “I think that without the support of products and Brent, the market may get dragged lower in the near term as it’s apparent that the market doesn’t care much about OPEC already jawboning about an extension of the deal,” Scott Shelton, a broker at ICAP, told Reuters.


The ironic thing is that while OPEC ponders more drastic action, there are signs that U.S. shale is actually not doing as well as everyone thought it would be at this point. Production is up, but signs of strain are showing. The rig count fell last week, after weeks of unimpressive gains. The slowdown suggests the industry is becoming more cautious, particularly with oil prices running out of steam.


In fact, some cracks are becoming visible in the Permian basin, often cited as the most attractive shale basin in the U.S. Costs are on the rise and some drillers are running into production problems. Production is up, but profits are scarce.


That could lead to a wholesale rethink for the industry - the days of explosive growth in the shale patch could be coming to an end. A growing number of investors are demanding that E&Ps slow down and focus on profitability, which will likely come at the expense of the industry’s blistering growth rate.


OPEC has yet to enjoy the fruit of this potential receding tide of shale drilling - oil looks softer than it did a few weeks ago and hedge funds and other money managers have pared back their bullish bets lately, a harbinger of more cautious sentiment.  


But while OPEC is nervous about near-term oil prices, and is planning “extraordinary measures,” they can at least take comfort in the fact that the shale bonanza is moderating.

Monday, October 9, 2017

The Geopolitical Consequences Of U.S. Oil Exports

Authored by Kent Moors via OilPrice.com,


Two crucial things happened last week.


The first you may have noticed – oil prices moved back up briefly.


As for the second, most so-called “experts” seemed to have missed.


See, the environment we’re seeing in energy markets is very different from what we saw only a week ago, when oil prices were also rising.


Because last week also saw – for the first time in world history – a reigning Saudi Arabian monarch in Moscow for talks with Russia’s head of state.


Historically, Russia has been much closer to Iran – Saudi Arabia’s main regional enemy.


Now, King Salman and President Putin are expected to endorse the plan to extend the OPEC-Russia deal to cut oil production and boost prices beyond the current end date of March 2018.


But that’s not all they’re going to talk about…


Other, more far-ranging matters will also be on the agenda, including the war in Syria.


And the catalyst for this huge shift in global geopolitics is surprisingly simple.


It’s all about America’s record-breaking oil exports…


Russia and Saudi Arabia Need Each Other… for Now


Now, there’s no indication that Russia and Saudi Arabia are on the road to an alliance on anything beyond oil prices.


Even then, that accord remains only as long as it is in the subjective interest of the parties.


Nonetheless, it is disquieting to Washington that any such prospects may be on the horizon… or that U.S. oil exports may be introducing a range of foreign policy concerns.


From an energy perspective, the main issue at hand is the OPEC-Russian deal to cap oil production, which is now almost certain to continue further than the agreed-on end date of March next year.


And after some concerns had been raised over individual OPEC members exceeding the quotas the deal assigned them, evidence is now emerging that the restraint is holding.


As I’ve several times before here in Oil & Energy Investor, there’s no genuine alternative.


The major global sources of oil need to allow the worldwide market to rebalance.


That’s the only genuine basis for stability and a slow increase in prices.


Now, with some of Libya’s oil production coming back on line, it may seem like there’s less flexibility for some producers to increase their crude output and still “hide” within the overall figures set by the cap accord.


But that’s ignoring four major factors that could cut into oil supply, and send prices higher…


Massive problems are accelerating in Venezuela, Nigerian extraction levels remain under threat from domestic instability, non-OPEC producer Mexico faces a continuing shortfall, and even the news from Libya – that a major field is coming back online – belies the ongoing civil unrest there, and lack of forward production expectations.


The international balance between supply and demand will provide a rising price.


Yet that rise will remain a gradual one.


And this balance doesn’t actually mean that there will only be exactly as much oil available as is needed at any given time.


That kind of “just in time” availability, where crude is lined only to meet immediate demand, is a certain recipe for high volatility and huge spikes in price.


Even a minor problem could create chaos in the markets.


Rather, a stable balance presupposes a continuing surplus of excess market volume.


That not only cushions the pricing dynamics from wide swings in demand, but it also allows producers the luxury of being able to predict the price range.


Anybody in the business will tell you that this predictability is far more important to maintaining profit margins than are the occasional large jumps in price.


An operator’s financial survivability requires that futures sales be calculated into the estimate of the cost of producing the oil and selling it on.


These prices, called “wellhead prices,” are the real revenue a producer receives in the first arms-length transaction as oil comes out of the ground.


These prices are also well below the market price quoted throughout a trading day.


U.S. Oil Production is at Record Highs


But the primary caveat in all of this talk about an emerging balance remains U.S. production.


It’s once again increasing and now has a more immediate impact on global pricing levels than has been the case previously.


That’s because American exports have become a major factor in the global market.


For some time, oil prices have not been determined by what occurs in developed markets of North America and Western Europe.


West Texas Intermediate (WTI) and Brent, the benchmark crude rates set in New York and London, may dictate daily trade. Yet the demand fueling the market is generated in developing areas worldwide.


Until recently, the U.S. only indirectly impacted upon the international determination of price.


In the past, the only effect came from how much the American market imported from elsewhere.


For over four decades, Congress banned the export of crude oil from the country on national security grounds.


Those restrictions resulted from the Arab oil embargo boycott of the U.S. during the 1973-74 Arab-Israeli War.


Today’s situation, where America has huge domestic extractable reserves of shale and tight oil, combined with significant improvements in production efficiency, has turned those security concerns obsolete.


There’s also the simple fact that no producing country in the world (with the possible exception of Iran, for political reasons) can afford not to sell to the U.S.


As a result, as part of a budget reconciliation two years ago, Congress lifted the ban on crude exports.


American refineries by that point were already leading the world in the export of processed oil products.


What followed was a quick move of American crude oil production back into the market…


Despite the Hurricanes, Oil Exports are Breaking Records


Exports had risen to a 1.1 million barrel a day level by the time Hurricane Harvey hit the Texas coast.


The hurricane slashed exports 60 percent. Refineries were also taken off line.


That combination should have pulverized crude oil prices, at least if you listened to the so-called “experts” on TV.


But that didn’t happen.


Instead, what happened next was nothing short of astounding.


Exports swiftly returned. Record levels were reached in each of the last two weeks.


As of last Friday, the U.S. was exporting 1.98 million barrels a day. The rising level of American volume in the broader market now has an impact on global price and the saliency of the OPEC-Russian agreement limiting production.


Because remember, U.S. production is not a party to that agreement.


The rising spread between WTI and Brent has also served as an additional inducement to increasing U.S. exports. The more international Brent prices have been increasing quicker than America’s WTI.


The difference, calculated as a percentage of WTI (the more accurate way of doing this), has now averaged more than 10 percent for the past 30 consecutive daily sessions – something that has not happened in over six years. Related: OPEC Producers Unmoved By U.S. Shale Threat In Asia


The advantage to American producers is simple. Exporting oil that costs less to produce at home into markets were the oil price is higher is a direct route to improving bottom lines.


As long as this situation remains, there will be additional U.S. production coming, because it’s profitable to extract and export.


And the more U.S. oil is exported, the less immediate effect higher production here has on domestic prices.


But this is also resulting in changes to foreign expectations.


Some of these are having spillover effects in other quarters…


Including sending Saudi Arabia and Russia into each other’s arms…


At least for now.

Wednesday, September 27, 2017

Why Political Correctness Fails (When What We Know "For Sure" Is Wrong)

Authored by Gail Tverberg via Our Finite World blog,


Most of us are familiar with the Politically Correct (PC) World View. William Deresiewicz describes the view, which he calls the “religion of success,” as follows:


There is a right way to think and a right way to talk, and also a right set of things to think and talk about. Secularism is taken for granted. Environmentalism is a sacred cause. Issues of identity - principally the holy trinity of race, gender, and sexuality - occupy the center of concern.


There are other beliefs that go with this religion of success:


  • Wind and solar will save us.

  • Electric cars will make transportation possible indefinitely.

  • Our world leaders are all powerful.

  • Science has all of the answers.

To me, this story is pretty much equivalent to the article, “Earth Is Flat and Infinite, According to Paid Experts,” by Chris Hume in Funny Times. While the story is popular, it is just plain silly.


In this post, I explain why many popular understandings are just plain wrong. I cover many controversial topics, including environmentalism, peer-reviewed literature, climate change models, and religion. I expect that the analysis will surprise almost everyone.


Myth 1: If there is a problem with the lack of any resource, including oil, it will manifest itself with high prices.


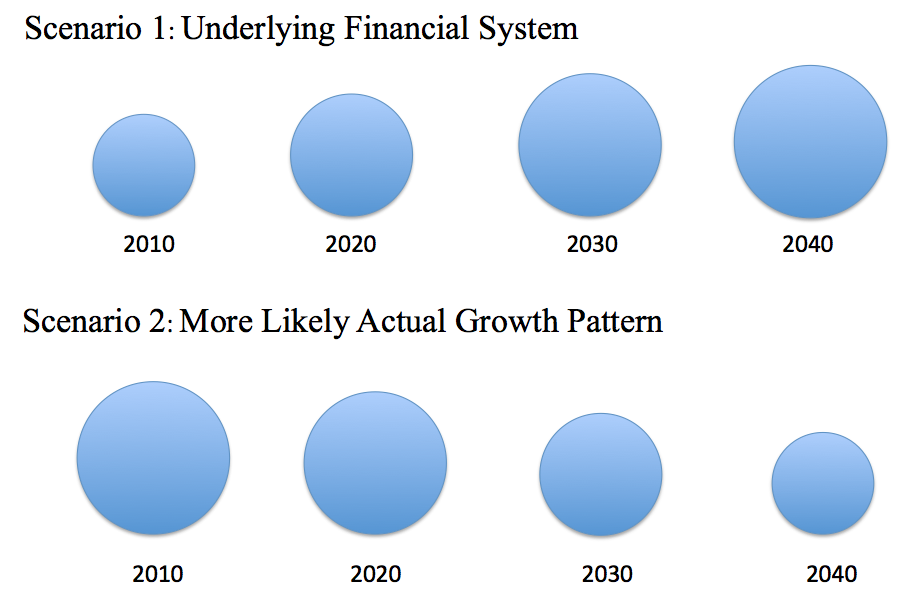
As we reach limits of oil or any finite resource, the problem we encounter is an allocation problem. 


What happens if economy stops growing

Figure 1. Two views of future economic growth. Created by author.


As long as the quantity of resources we can extract from the ground keeps rising faster than population, there is no problem with limits. The tiny wedge that each person might get from these growing resources represents more of that resource, on average. Citizens can reasonably expect that future pension promises will be paid from the growing resources. They can also expect that, in the future, the shares of stock and the bonds that they own can be redeemed for actual goods and services.


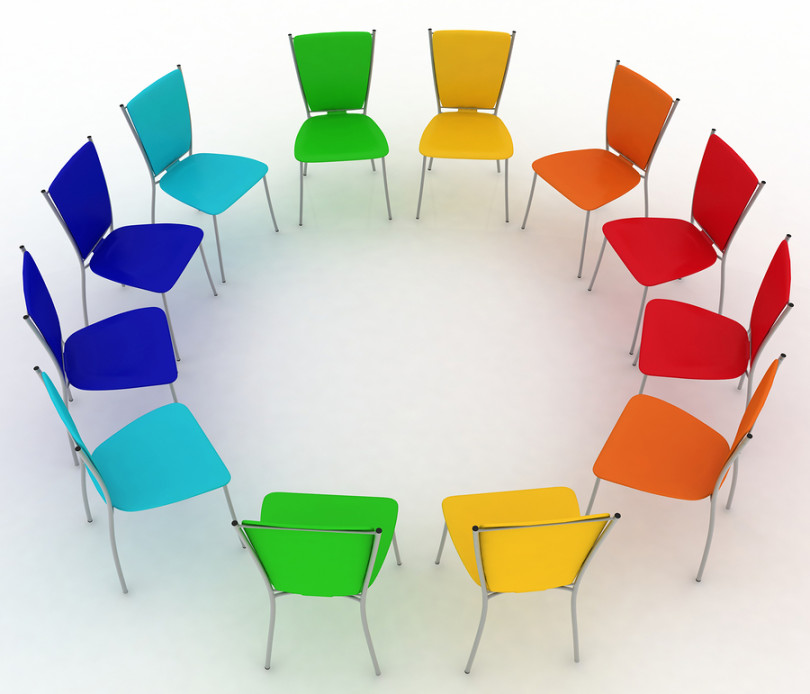
If the quantity of resources starts to shrink, the problem we have is almost a “musical chairs” type of problem.


Figure 2. Circle of chairs arranged for game of musical chairs. Source


In each round of a musical chairs game, one chair is removed from the circle. The players in the game must walk around the outside of the circle. When the music stops, all of the players scramble for the remaining chairs. Someone gets left out.


The players in today’s economic system include


  • High paid (or elite) workers

  • Low paid (or non-elite) workers

  • Businesses

  • Governments

  • Owners of assets (such as stocks, bonds, land, buildings) who want to sell them and exchange them for today’s goods and services

If there is a shortage of a resource, the standard belief is that prices will rise and either more of the resource will be found, or substitution will take place. Substitution only works in some cases: it is hard to think of a substitute for fresh water. It is often possible to substitute one energy product for another. Overall, however, there is no substitute for energy. If we want to heat a substance to produce a chemical reaction, we need energy. If we want to move an object from place to place, we need energy. If we want to desalinate water to produce more fresh water, this also takes energy.


The world economy is a self-organized networked system. The networked system includes businesses, governments, and workers, plus many types of energy, including human energy. Workers play a double role because they are also consumers. The way goods and services are allocated is determined by “market forces.” In fact, the way these market forces act is determined by the laws of physics. These market forces determine which of the players will get squeezed out if there is not enough to go around.


Non-elite workers play a pivotal role in this system because their number is so large. These people are the chief customers for goods, such as homes, food, clothing, and transportation services. They also play a major role in paying taxes, and in receiving government services.


History says that if there are not enough resources to go around, we can expect increasing wage and wealth disparity. This happens because increased use of technology and more specialization are workarounds for many kinds of problems. As an economy increasingly relies on technology, the owners and managers of the technology start receiving higher wages, leaving less for the workers without special skills. The owners and managers also tend to receive income from other sources, such as interest, dividends, capital gains, and rents.


When there are not enough resources to go around, the temptation is to use technology to replace workers, because this reduces costs. Of course, a robot does not need to buy food or a car. Such an approach tends to push commodity prices down, rather than up. This happens because fewer workers are employed; in total they can afford fewer goods. A similar downward push on commodity prices occurs if wages of non-elite workers stagnate or fall.


If wages of non-elite workers are lower, governments find themselves in increasing difficulty because they cannot collect enough taxes for all of the services that they are asked to provide. History shows that governments often collapse in such situations. Major defaults on debt are another likely outcome (Figure 3). Pension holders are another category of recipients who are likely to be “left out” when the game of musical chairs stops.


Figure 3 – Created by Author.


The laws of physics strongly suggest that if we are reaching limits of this type, the economy will collapse. We know that this happened to many early economies. More recently, we have witnessed partial collapses, such as the Depression of the 1930s. The Depression occurred when the price of food dropped because mechanization eliminated a significant share of human hand-labor. While this change reduced the price of food, it also had an adverse impact on the buying-power of those whose jobs were eliminated.


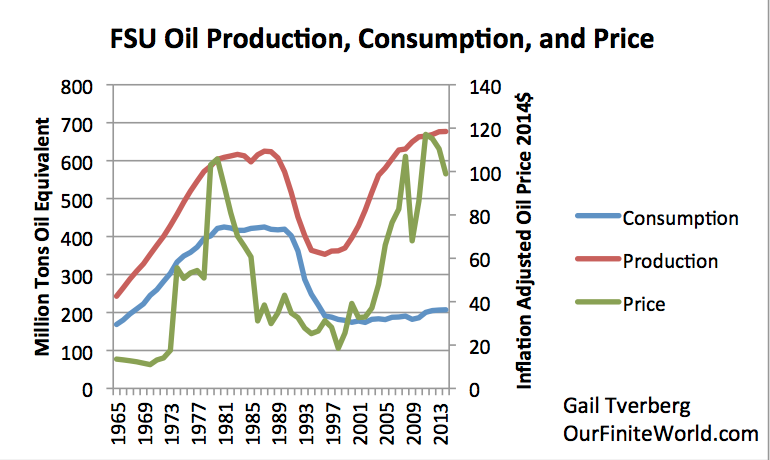
The collapse of the Soviet Union is another example of a partial collapse. This collapse occurred as a follow-on to the low oil prices of the 1980s. The Soviet Union was an oil exporter that was affected by low oil prices. It could continue to produce for a while, but eventually (1991) financial problems caught up with it, and the central government collapsed.


Figure 4. Oil consumption, production, and inflation-adjusted price, all from BP Statistical Review of World Energy, 2015.


Low prices are often a sign of lack of affordability. Today’s oil, coal, and natural gas prices tend to be too low for today’s producers. Low energy prices are deceptive because their initial impact on the economy seems to be favorable. The catch is that after a time, the shortfall in funds for reinvestment catches up, and production collapses. The resulting collapse of the economy may look like a financial collapse or a governmental collapse.


Oil prices have been low since late 2014. We do not know how long low prices can continue before collapse. The length of time since oil prices have collapsed is now three years; we should be concerned.


Myth 2. (Related to Myth 1) If we wait long enough, renewables will become affordable.


The fact that wage disparity grows as we approach limits means that prices can’t be expected to rise as we approach limits. Instead, prices tend to fall as an increasing number of would-be buyers are frozen out of the market. If in fact energy prices could rise much higher, there would be huge amounts of oil, coal and gas that could be extracted.


Figure 5. IEA Figure 1.4 from its World Energy Outlook 2015, showing how much oil can be produced at various price levels, according to IEA models.


There seems to be a maximum affordable price for any commodity. This maximum affordable price depends to a significant extent on the wages of non-elite workers. If the wages of non-elite workers fall (for example, because of mechanization or globalization), the maximum affordable price may even fall.


Myth 3. (Related to Myths 1 and 2) A glut of oil indicates that oil limits are far away. 


A glut of oil means that too many people around the world are being “frozen out” of buying goods and services that depend on oil, because of low wages or a lack of job. It is a physics problem, related to ice being formed when the temperature is too cold. We know that this kind of thing regularly happens in collapses and partial collapses. During the Depression of the 1930s, food was being destroyed for lack of buyers. It is not an indication that limits are far away; it is an indication that limits are close at hand. The system can no longer balance itself correctly.


Myth 4: Wind and solar can save us.


The amount of energy (other than direct food intake) that humans require is vastly higher than most people suppose. Other animals and plants can live on the food that they eat or the energy that they produce using sunlight and water. Humans deviated from this simple pattern long ago–over 1 million years ago.


Unfortunately, our bodies are now adapted to the use of supplemental energy in addition to food. The use of fire allowed humans to develop differently than other primates. Using fire to cook some of our food helped in many ways. It freed up time that would otherwise be spent chewing, providing time that could be used for tool making and other crafts. It allowed teeth, jaws and digestive systems to be smaller. The reduced energy needed for maintaining the digestive system allowed the brain to become bigger. It allowed humans to live in parts of the world where they are not physically adapted to living.


In fact, back at the time of hunter-gatherers, humans already seemed to need three times as much energy total as a correspondingly sized primate, if we count burned biomass in addition to direct food energy.


Figure 6 – Created by author.


“Watts per Capita” is a measure of the rate at which energy is consumed. Even back in hunter-gatherer days, humans behaved differently than similar-sized primates would be expected to behave. Without considering supplemental energy, an animal-like human is like an always-on 100-watt bulb. With the use of supplemental energy from burned biomass and other sources, even in hunter-gatherer times, the energy used was equivalent to that of an always-on 300-watt bulb.


How does the amount of energy produced by today’s wind turbines and solar panels compare to the energy used by hunter-gatherers? Let’s compare today’s wind and solar output to the 200 watts of supplemental energy needed to maintain our human existence back in hunter-gatherer times (difference between 300 watts per hour and 100 watts per hour). This assumes that if we were to go back to hunting and gathering, we could somehow collect food for everyone, to cover the first 100 watts per hour. All we would need to do is provide enough supplemental energy for cooking, heating, and other very basic needs, so we would not have to deforest the land.


Conveniently, BP gives the production of wind and solar in “terawatt hours.” If we take today’s world population of 7.5 billion, and multiply it by 24 hours a day, 365.25 days per year, and 200 watts, we come to needed energy of 13,149 terawatt hours per year. In 2016, the output of wind was 959.5 terawatt hours; the output of solar was 333.1 terawatt hours, or a total of 1,293 terawatt hours. Comparing the actual provided energy (1,293 tWh) to the required energy of 13,149 tWh, today’s wind and solar would provide only 9.8% of the supplemental energy needed to maintain a hunter-gatherer level of existence for today’s population. 


Of course, this is without considering how we would continue to create wind and solar electricity as hunter-gatherers, and how we would distribute such electricity. Needless to say, we would be nowhere near reproducing an agricultural level of existence for any large number of people, using only wind and solar. Even adding water power, the amount comes to only 40.4% of the added energy required for existence as hunter gatherers for today’s population.


Many people believe that wind and solar are ramping up rapidly. Starting from a base of zero, the annual percentage increases do appear to be large. But relative to the end point required to maintain any reasonable level of population, we are very far away. A recent lecture by Energy Professor Vaclav Smil is titled, “The Energy Revolution? More Like a Crawl.”


Myth 5. Evaluation methods such as “Energy Returned on Energy Invested” (EROI) and “Life Cycle Analyses (LCA)” indicate that wind and solar should be acceptable solutions. 


These approaches are concerned about how the energy used in creating a given device compares to the output of the device. The problem with these analyses is that, while we can measure “energy out” fairly well, we have a hard time determining total “energy in.” A large share of energy use comes from indirect sources, such as roads that are shared by many different users.


A particular problem occurs with intermittent resources, such as wind and solar. The EROI analyses available for wind and solar are based on analyses of these devices as stand-alone units (perhaps powering a desalination plant, on an intermittent basis). On this basis, they appear to be reasonably good choices as transition devices away from fossil fuels.


EROI analyses don’t handle the situation well when there is a need to add expensive infrastructure to compensate for the intermittency of wind and solar. This situation tends to happen when electricity is added to the grid in more than small quantities. One workaround for intermittency is adding batteries; another is overbuilding the intermittent devices, and using only the portion of intermittent electricity that comes at the time of day and time of year when it is needed. Another approach involves paying fossil fuel providers for maintaining extra capacity (needed both for rapid ramping and for the times of year when intermittent resources are inadequate).


Any of these workarounds is expensive and becomes more expensive, the larger the percentage of intermittent electricity that is added. Euan Mearns recently estimated that for a particular offshore wind farm, the cost would be six times as high, if battery backup sufficient to even out wind fluctuations in a single month were added. If the goal were to even out longer term fluctuations, the cost would no doubt be higher. It is difficult to model what workarounds would be needed for a truly 100% renewable system. The cost would no doubt be astronomical.


When an analysis such as EROI is prepared, there is a tendency to leave out any cost that varies with the application, because such a cost is difficult to estimate. My background is in actuarial work. In such a setting, the emphasis is always on completeness because after the fact, it will become very clear if the analyst left out any important insurance-related cost. In EROI and similar analyses, there is much less of a tieback to the real world, so an omission may never be noticed. In theory, EROIs are for multiple purposes, including ones where intermittency is not a problem. The EROI modeler is not expected to consider all cases.


Another way of viewing the issue is as a “quality” issue. EROI theory generally treats all types of energy as equivalent (including coal, oil, natural gas, intermittent electricity, and grid-quality electricity). From this perspective, there is no need to correct for differences in types of energy output. Thus, it makes perfect sense to publish EROI and LCA analyses that seem to indicate that wind and solar are great solutions, without any explanation regarding the likely high real-world cost associated with using them on the electric grid.


Myth 6. Peer reviewed articles give correct findings.


The real story is that peer reviewed articles need to be reviewed carefully by those who use them. There is a very significant chance that errors may have crept in. This can happen because of misinterpretation of prior peer reviewed articles, or because prior peer reviewed articles were based on “thinking of the day,” which was not quite correct, given what has been learned since the article was written. Or, as indicated by the example in Myth 5, the results of peer reviewed articles may be confusing to those who read them, in part because they are not written for any particular audience.


The way university research is divided up, researchers usually have a high level of specialized knowledge about one particular subject area. The real world situation with the world economy, as I mentioned in my discussion of Myth 1, is that the economy is a self-organized networked system. Everything affects everything else. The researcher, with his narrow background, doesn’t understand these interconnections. For example, energy researchers don’t generally understand economic feedback loops, so they tend to leave them out. Peer reviewers, who are looking for errors within the paper itself, are likely to miss important feedback loops as well.


To make matters worse, the publication process tends to favor results that suggest that there is no energy problem ahead. This bias can come through the peer review process. One author explained to me that he left out a certain point from a paper because he expected that some of his peer reviewers would come from the Green Community; he didn’t want to say anything that might offend such a reviewer.


This bias can also come directly from the publisher of academic books and articles. The publisher is in the business of selling books and journal articles; it does not want to upset potential buyers of its products. One publisher made it clear to me that its organization did not want any mention of problems that seem to be without a solution. The reader should be left with the impression that while there may be issues ahead, solutions are likely to be found.


In my opinion, any published research needs to be looked at very carefully. It is very difficult for an author to move much beyond the general level of understanding of his audience and of likely reviewers. There are financial incentives for authors to produce PC reports, and for publishers to publish them. In many cases, articles from blogs may be better resources than academic articles because blog authors are under less pressure to write PC reports.


Myth 7. Climate models give a good estimate of what we can expect in the future.


There is no doubt that climate is changing. But is all of the hysteria about climate change really the correct story?


Our economy, and in fact the Earth and all of its ecosystems, are self-organized networked systems. We are reaching limits in many areas at once, including energy, fresh water, the number of fish that can be extracted each year from oceans, and metal ore extraction. Physical limits are likely to lead to financial problems, as indicated in Figure 3. The climate change modelers have chosen to leave all of these issues out of their models, instead assuming that the economy can continue to grow as usual until 2100. Leaving out these other issues clearly can be expected to overstate the impact of climate change.


The International Energy Agency is very influential with respect to which energy issues are considered. Between 1998 and 2000, it did a major flip-flop in the importance of energy limits. The IEA’s 1998 World Energy Outlook devotes many pages to discussing the possibility of inadequate oil supplies in the future. In fact, near the beginning, the report says,


Our analysis of the current evidence suggests that world oil production from conventional sources could peak during the period 2010 to 2020.


The same report also mentions Climate Change considerations, but devotes many fewer pages to these concerns. The Kyoto Conference had taken place in 1997, and the topic was becoming more widely discussed.


In 1999, the IEA did not publish World Energy Outlook. When the IEA published the World Energy Outlook for 2000, the report suddenly focused only on Climate Change, with no mention of Peak Oil. The USGS World Petroleum Assessment 2000 had recently been published. It could be used to justify at least somewhat higher future oil production.


I will be the first to admit that the “Peak Oil” story is not really right. It is a halfway story, based on a partial understanding of the role physics plays in energy limits. Oil supply does not “run out.” Peak Oilers also did not understand that physics governs how markets work–whether prices rise or fall, or oscillate. If there is not enough to go around, some of the would-be buyers will be frozen out. But Climate Change, as our sole problem, or even as our major problem, is not the right story, either. It is another halfway story.


One point that both Peak Oilers and the IEA missed is that the world economy doesn’t really have the ability to cut back on the use of fossil fuels significantly, without the world economy collapsing. Thus, the IEA’s recommendations regarding moving away from fossil fuels cannot work. (Shifting energy use among countries is fairly easy, however, making individual country CO2 reductions appear more beneficial than they really are.) The IEA would be better off talking about non-fuel changes that might reduce CO2, such as eating vegetarian food, eliminating flooded rice paddies, and having smaller families. Of course, these are not really issues that the International Energy Association is concerned about.


The unfortunate truth is that on any difficult, interdisciplinary subject, we really don’t have a way of making a leap from lack of knowledge of a subject, to full knowledge of a subject, without a number of separate, partially wrong, steps. The IPCC climate studies and EROI analyses both fall in this category, as do Peak Oil reports.


The progress I have made on figuring out the energy limits story would not have been possible without the work of many other people, including those doing work on studying Peak Oil and those studying EROI. I have also received a lot of “tips” from readers of OurFiniteWorld.com regarding additional topics I should investigate. Even with all of this help, I am sure that my version of the truth is not quite right. We all keep learning as we go along.


There may indeed be details of this particular climate model that are not correct, although this is out of my area of expertise. For example, the historical temperatures used by researchers seem to need a lot of adjustment to be usable. Some people argue that the historical record has been adjusted to make the historical record fit the particular model used.


There is also the issue of truing up the indications to where we are now. I mentioned the problem earlier of EROI indications not having any real world tie; climate model indications are not quite as bad, but they also seem not to be well tied to what is actually happening.


Myth 8. We don’t need religion; our leaders are all knowing and all powerful.


We are fighting a battle against the laws of physics. Expecting our leaders to win in the battle against the laws of physics is expecting a huge amount. Some of the actions of our leaders seem extraordinarily stupid. For example, if falling interest rates have postponed peak oil, then proposing to raise interest rates, when we have not fixed the underlying oil depletion problem, seems very ill-advised.


Everything I have seen indicates that there is a literal Higher Power governing our world economy. It is the Laws of Physics that govern the world economy. The Laws of Physics affect the world economy in many ways. The economy is a dissipative structure. Energy inputs allow the economy to remain in an “out of equilibrium state” (that is, in a growing state), for a very long period.


Eventually the ability of any economy to grow must come to an end. The problem is that it requires increasing amounts of energy to fight the growing “entropy” (higher energy cost of extraction, need for growing debt, and rising pollution levels) of the system. The economy must come to an end, just as the lives of individual plants and animals (which are also dissipative structures) must come to an end.


People throughout the ages have been in awe of how this system that provides growth works. We get energy from the sun. This solar energy helps grow our food. It allows the physical growth of humans. It allows the growth of ecosystems and of economies. Humans, ecosystems, and economies seem permanent, but eventually they all must collapse. In physics terms, they are all dissipative structures.


Humans have been in awe of the self-organizing property permitted by flows of energy for as long as humans have had the ability to think abstract thoughts. These flows allow a newly created whole to be greater than the sum of their parts. For example, babies start from a small beginning and mature into adults. Musical notes go together to form recognizable melodies. Physical movements go together to form dances. Awe for this phenomenon seems to be one of the origins of religion.


Another reason for religions is a need for hierarchical structure within an economy. We know that animal groups very often have “pecking orders.” Adding a god provides a convenient way of adding a “top level” to the pecking order. Of course, if leaders can convince members of the group that they are all knowing and that science can provide all of the answers, then the top level provided by religion is not needed.


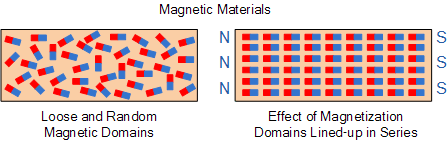
A third reason for religions is to help align the thoughts of members in a particular way. Most of us are aware of the power of magnetized materials.


Figure 7. Source.


To some extent, the same power exists when the belief systems of groups of people can be aligned in the same direction. For example, teachers find it much easier to teach large groups of students, if parents have emphasized the importance of school and the need for respect for teachers. A military leader can attack another country, if soldiers follow orders. A group of generally uncivilized people can learn the benefit of working with others, if proper instruction is given.


What has been astounding to me, as I have looked into the situation, is that the scientific evidence seems to point in the direction of a literal Higher Power governing our Universe. It is not clear whether this higher power is the Laws of Physics, or whether it is some outside “God” that created the Laws of Physics.


In the past, many researchers assumed that the Universe was a closed energy system, irreversibly headed toward a cold, dark end. Recent research indicates that the Universe is ever-expanding, and in fact, seems to be expanding at an accelerating rate. While individual dissipative structures are constantly encountering more and more entropy, the universe as a whole is perhaps expanding rapidly enough to “outrun” growing entropy. Thus, it can behave as an always-open system. This always-open energy system allows many types of objects to self-organize and grow, at least for a time. These objects behave as dissipative structures, each having a beginning and an end.


We really don’t know whether the Universe had a beginning. Some research suggests that it did not. Others believe it began with a Big Bang.


Within the Universe, the earth seems extremely unusual. In fact, it is not clear that there is any other planet that has exactly the right conditions for complex life. A recent American Scientist article discusses this issue. The book Rare Earth: Why Complex Life Is Uncommon in the Universe points out the huge number of coincidences that were necessary for complex life to form and flourish.


Within the Earth, and perhaps within the Universe as a whole, human economies are the most energy-dense form of structure found.


Figure 8. Image similar to ones shown in Eric Chaisson’s 2001 book, Cosmic Evolution: The Rise of Complexity in Nature.


Thus, in some sense, we humans and our economies may, in some sense, represent the current upper bound on development in the Universe.


We humans live on Earth. It is easy for us to think that our primary purpose in life is to care for and protect the Earth. Unfortunately, with our need for supplemental energy, this is not possible. Even at an early date, our need for resources exceeded what was sustainable. Joshua (in Joshua 17:14-18 relating to the period around 1400 BCE) instructs the tribes of Joseph to clear the trees from the hill country to have enough land for his tribe. This practice was clearly unsustainable; it would lead to erosion of the soil on hilltops. Even at that early date, high population and the need for resources to provide for this high population was conflicting with earth’s sustainability.


If our God is either the Laws of Physics, or some force giving rise to the Laws of Physics, then our God is really the God of the Universe. The limitations of the current Earth are no problem. God (or the Laws of Physics) could create a new Earth, or 1 million new Earths, if He chose to. Thus, from God’s point of view, it is not clear that there is any point to today’s environmentalism. There is a need not to poison ourselves, but “saving the earth” for other species after humans, or for a new set of humans who somehow will use much less energy, doesn’t make much sense. Humans can’t use much less energy; even if we could, our energy use would always be on an upward slope, headed to precisely where we are now.


There are many things that we can’t know for certain. Does this God want/expect us to worship him? Does this God plan an afterlife for some or all of the humans on Earth today? Obviously, if God (or the Laws of Physics) could create the Earth, God could also create other structures as well–possibly a “Heaven.” It is not clear to me that any one of today’s religions has a monopoly on insights regarding what is expected. A person might argue that we need not worry about religion at all, except for the fellowship it provides and the insights it offers regarding how early people coped with their difficulties.


Myth 9. The texts of religious groups around the world are literally true.


The texts of religious groups are true in the same sense that peer reviewed scientific literature is true. They represent, more or less, the best thinking of the day on a particular subject. This certainly does not mean that they are literally true.


We need to read religious texts in the context that they were written. In the earliest days, religious texts represented stories that people passed down from one generation to the next. These stories represented insights that these early people had gained. No one at that time was too concerned about authorship. If a story says, “God said,” it could also mean, “We think that this is something that God might have said.”


Literary styles were very different, back in an era before people pretended to have scientific knowledge. People created stories illustrating some aspect of a particular phenomenon. These stories were not supposed to fully describe what happened. This is why Genesis features two different creation stories.


The Bible makes liberal use of hyperbole and exaggeration. It is hard for people who are not familiar with the original language to understand how stories were intended to be interpreted. Is the concept of Hell added, primarily to provide a contrast to Heaven? In the Old Testament, the number of words in the ancient Hebrew language is much smaller than in today’s languages. This, by itself, makes direct translation difficult.


The earliest religious stories explained how God was perceived at that time. As people became more settled, their views changed. People were getting more “civilized.” Population densities were rising. The best beliefs in an early period may not have had relevance for a later period. This is why most religions have had reformers. Sometimes new writings are added. At other times, the way the writings are interpreted changes. This is why there seems to be a bizarre progression of stories from the Old Testament to the New Testament; new stories needed to be added to supplement and replace old ways of thinking.


Some of the things that early people discovered have not been understood by environmentalists. Genesis 1:28 says,


God blessed them and said to them, “Be fruitful and increase in number; fill the earth and subdue it. Rule over the fish in the sea and the birds in the sky and over every living creature that moves on the ground.”


The early people had figured out that humans were indeed different from other animals and plants. Their use of supplemental energy gave them power over other creatures. Their numbers could (and indeed, did) increase. Early authors were documenting how the world really worked. We later humans have been too blind to see the real situation. It is more pleasant for us to think that somehow we are just like other animals, except perhaps smarter and more in control. With our greater knowledge, we could somehow have avoided an increase in our numbers, if we had only planned better. The laws of physics say this cannot happen; our higher energy use dictates who will win the battle for resources.


The early religious stories were not too different from Peak Oil and Climate Change. They were sort of right. They gave partial insight. They were the best the authors could do at the time.


The ancient religious documents could not tell the whole story at once. New groups would gradually add more insights to the developing story, providing a better understanding of what was truly important for people living in a later period.


Conclusion


In practice, people need a religion or a religion-substitute. People need a basic set of beliefs with which to order their lives.


Our leaders today have proposed the Religion of Success, with its belief in Science, and the power of today’s leaders, as the new religion. This religion has appeal, because it denies the limits we are up against. Life will continue, as if we lived on a flat earth with unlimited resources. This story is pleasant, but unfortunately not true.


Donald Trump, with his version of conservatism, presents another religion. This religion seems to be focused on justifying the allocation of wealth away from the poor, toward the rich, through tax breaks for corporations and the wealthy. This is part of the process of “freezing out” the poor people of the world, when there are not enough resources to go around.


It is hard for me to support Trumpism, even though I recognize that in the animal world, the expected outcome when there are not enough resources to go around is “survival of the best-adapted.” If our concern is leaving energy resources in the ground for future generations, transferring buying power from the poor to the rich is a way of collapsing the economy quickly, while considerable resources remain in the ground. The fact that wealthy people are favored ensures that at least some people will survive.


China and Japan both have what are close to state religions, created by their leaders. School children learn stories regarding what is important, based on what state leaders tell them. In Japan, school children visit religious sites, and learn the proper religious observances. They also learn rules about what is expected of them–always be polite; respect those in charge; don’t eat food on the street; never leave any food wrappers on the ground. In many ways, these religions are probably not too different from today’s Religion of Success.


I personally am not in favor of religions that originate from political groups. I would prefer the “old fashioned” religions based on ancient documents from one or another of the world’s religions. We are clearly facing a difficult time ahead. Perhaps early people had insights regarding how to deal with troubled times. Admittedly, we don’t know for certain that heaven can be in our future. But when things look bleak, it is helpful to see the possibility of a reasonable outcome.


Furthermore, religious groups offer the possibility of finding a group of like-minded individuals to make friends with. We need all of the support we can get as we go through troubled times.