Showing posts with label Eton Park. Show all posts

Thursday, September 28, 2017

Whitney Tilson Shuts His Hedge Fund... Again

Back in the summer of 2012, we had some fun when we reported that Whitney Tilson - the consummate, if always late immitator of other prominent investors especially Warren Buffett and Bill Ackman - following several years of abysmal returns, closed his then-hedge fund T2 (with Glenn Tongue), splitting off into his own, oddly-named venture, Kase Capital. Well, Whitney - who in recent years was better known for his bizarre family photos from Africa than managing money- has done it again and according to the WSJ, Tilson closed his hedge fund... again, "the latest high-profile investor to close shop amid an extended period of disappointing returns for the industry."


As the WSJ adds, Tilson, 50, shared his decision with clients (apparently he still had some) on Sunday. His latest hedge fund, Kase Capital, which was managing a whopping 50 million at the time of closure, and down from a peak of $180 million, lost about 8% so far this year, a more than 20% underperformance relative to the S&P YTD gain of more than 13%.


As the WSJ adds sarcastically, "while he ran a relatively small fund, Mr. Tilson was a well-known hedge-fund manager thanks to television and conference appearances, as well as books and regular writing about investing and other topics." In other words, Tilson was not so much a "hedge fund manager" as its straight-to-CNBC marketer, and the results have confirmed it.


In an amusing twist, in 2016 Tilson - a staunch never-Trumpter - inexplicably found himself the subject of scathing criticism by Elizabeth Warren, after Tilson expressed modest public support of some of President Donald Trump’s cabinet and other appointments from the banking world, "even though Mr. Tilson is a lifelong Democrat who voted for Hillary Clinton."


“The next four years are going to be a bonanza for the Whitney Tilsons of the world,” the Massachusetts Democrat said at the time. She later apologized to Mr. Tilson for her criticism.


And so Tilson joins a long procession of managers, some of whom managed actual real money, who decided that it was impossible to navigate these centrally planned markets and an exit was the noble way to go.


He is hardly the last one: in the past several months, a couple of well-known hedge funds have closed. Among them, investor Eric Mindich closed his $7 billion hedge-fund firm, Eton Park Capital Management LP, billionaire Richard Perry shuttered his hedge-fund firm and Hugh Hendry exited his flagship fund in London. “I died in active combat,” Mr. Hendry told Bloomberg at the time. “The last three months were harrowing.”


Many more closures are coming as investors redeem cash ahead of year-end at a pace not seen since the financial crisis.


As for Whitney, who somehow managed money for more than 18 years, the WSJ says that he is "expected to manage his own money." Considering Tilson was one of the founding, and most vocal members of "Patriotic Millionaires" group begging to be taxed more, we assume he does, in fact, have money to manage (we are not so sure about his clients) and this wasn"t just yet another marketing gimmick from the now former hedge fund manager.


Whitney"s full farewell letter below:


Dear friends,


I recently decided to close my funds and return capital to investors (excerpts from my letter to them are below). It was a hard decision, but the right one.


Now, I am filled with enthusiasm about what I will do with the second half of my life. What might that be? I’m not sure, but I want to share a few thoughts – and would be grateful for your feedback and ideas.


I’ve been working full time for more than 30 years, almost all of that time in an entrepreneurial capacity. While my one “regular” job early in my career was a good experience, I like being independent and plan to remain so. My goal is to find opportunities that are personally interesting, give me the chance to collaborate with great people, and are sufficiently remunerative (contrary to Elizabeth Warren’s belief, I am most definitely not a billionaire!).


I expect that most of my work will continue to be in the investment field, as I still love it and am confident that I can put my energy and 18 years of experience to good use. While I no longer intend to manage others’ money, I’m exploring a number of ideas, such as:


1) Unearthing a few great investment opportunities each year, in which I can invest personally as well as share with a few others;
2) Serving on corporate boards;
3) Doing consulting in areas in which I have expertise such as capital allocation, strategy, and activist investing; and
4) Teaching and mentoring young value investors via writings, videos and seminars.


I would welcome your advice and suggestions, so please don’t hesitate to email me at WTilson@kasecapital.com or call me at (646) 258-0687.


Sincerely yours,


Whitney


Warning: Danger Lurks Here

By Chris at www.CapitalistExploits.at


Take a look at the volume of stocks listed vs. indexes listed going all the way back to the days of bellbottoms, loud hair, and orange wallpaper.


Since 1995, the supply of stocks, particularly in the US, has been shrinking faster than Trump"s approval ratings. At the same time, the number of indexes have exploded like one of Kim"s shiny new missiles.


Why?


In a falling interest rate environment, the twin pressures of reduced returns and relative cost pressures have meant that investors, in order to make a buck, have flooded into the low fee structures offered by passive strategies. These include indexing, ETFs, and those truly insane creatures I"ve written about before: low volatility ETFs.


But what about those alpha generating hedge funds? Aren"t they meant to be smart and able to beat the market... any market?


Those alpha generating hedge funds have things called LPs. And though LPs may be smarter, and certainly wealthier than Joe Sixpack, they"re no less human. And human attention span and patience level has been in decline... correlated no doubt with the rise of social media and the Kardashian crowd. Like a virus, it infects everything.


As performance from hedge funds has been poor relative to the benchmarks, a self reinforcing situation where hedge funds, in order to ensure LPs don"t redeem, have landed up hugging the indexes.


This is the exact opposite of what hedge funds were meant to do, of course. In many cases, they themselves are simply buying the indexes, trying desperately to figure out how the hell they"re going to survive through the next quarter but determined simply NOT to underperform the index. It"s a losing strategy no matter how you slice and dice it.


For those hedge funds who refuse to chase the indexes... Well, they are now fighting the tidal wave of capital that has been shifting into passive investments, which forces those passive investments even higher.


This, in turn, leaves active hedge funds who refuse to get sucked in with increasingly substandard returns. They can explain until they"re blue in the face why certain indexes make no sense but when those indexes just keep rising day after day, month after month, it becomes a very tough stance to keep. Redemptions follow, and so by doing the right thing, they"re punished. And by doing the wrong thing (following the mob), they may get to stay alive just a little longer and this is what many have resorted to.


We all know that at some point there are no new buyers available to enter the market and hoo boy, do we then have a problem.


So... you either join the party or you leave the party.


The last to leave the party is Hugh Hendry and his baby Eclectica.


Hugh Hendry Murders His Hedge Fund


Og aye, tis tae tough


Hugh follows Eton Park and Perry Capital to name but a few more.


Paul Singer of Elliot Management fame put it well in his July investor letter to stakeholders.


"In a passive investing world, small shareholders have little-to-no voice and no realistic possibility of banding together, while the biggest shareholders have no (repeat, no) skin in the game so long as the money manager does not underperform the index."


Make no mistake, the rise of passive indexing is a bubble in dumb money.


We have a situation where the market is becoming completely lopsided and increasingly so at a blistering pace.


If it gets anymore lopsided, it"s going to be upside down. What"s more, the market participants have no interest or even determination of valuations.


An index doesn"t give an isht what the P/E ratio of any stock included in the index is, and the investors buying it have even less idea. It doesn"t care if the aggregate of stocks sitting inside its womb are over or indeed undervalued. It"s just a dumb bloody index, and you can"t blame it anymore than I can blame my dog for not understanding Shakespeare.


Those investing in passive have done so partly due to relative fee differentials, partly due to performance. But now also dangerously so... due to increasing inflows, which have continued to push values higher.


Now, having markets or sectors get silly is obviously as normal as a peanut butter sandwich, and provided you"re aware of it, we"ve little to worry about.


But what"s more frightening than the Kardashians in skinny pants is that as capital has fed into passive, the usual countering forces (active managers) of the market have been leaving the party, which has left the passive world to increasingly swell like a neglected infected wound.


What we need to think about is that increasingly there is no active market to stabilise this. It"s akin to having a 5-year-old"s party, inviting a troop of the critters, and then promptly sending all the parents down to the pub for a few hours.


Just as short sellers provide a balance to a market so, too, active management (who incidentally typically have skin in the game) have always provided a stabiliser to the overall market. What happens when the stabilisers all leave the room?


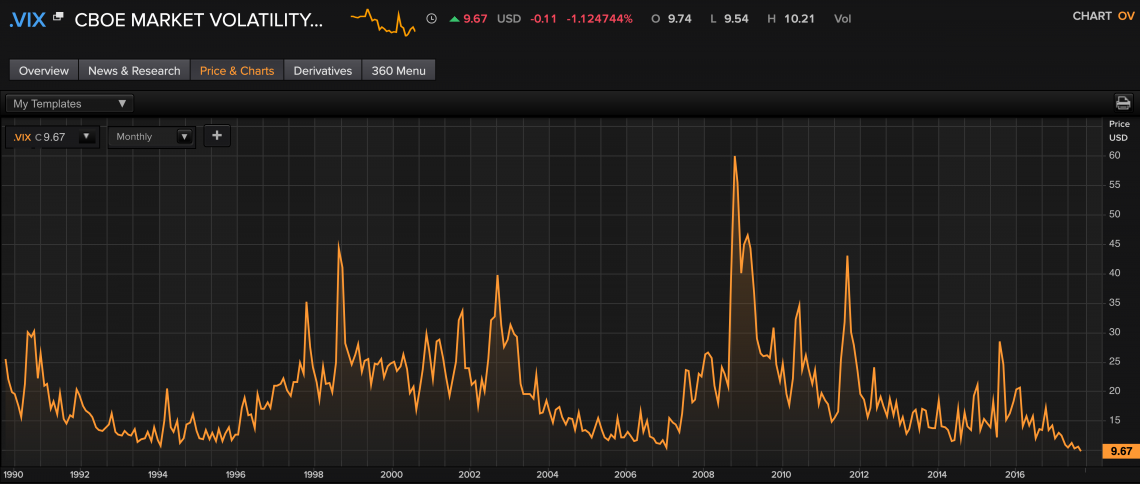
We can see this manifesting itself in the volatility index. As more capital enters at a steady pace so, too, the volatility falls.


And here"s the thing. The algos constantly feed back the daily data to recalculate their probabilities (read this article on VAR shocks). Risk? Nah!


At the extreme of the passive world sits volatility.


Selling volatility works really well. Just ask Neiderhoffer who has made godawful amounts doing it over the years.


Look closely, though, and you notice that even Neiderhoffer, who knows what game he"s playing, blows himself up spectacularly from time to time... and I mean complete armageddon wipeout stuff. Until that blow up comes, though, you just keep plugging away at it day after day and it just keeps paying you... day after day. You make money, make money... and then, well...


It all turns to isht and blows up in your face.


My friend Mark Yusko from Morgan Creek Capital places capital with the smartest strategies and hedge funds - active capital.


Who"s willing to bet with me that over the next decade being long smart active strategies and short passive (low volatility ETFs) will be a winning trade?


Wow Poll - 27 Sep


Cast your vote here and also see what others think


- Chris


“What could be more advantageous in an intellectual contest – whether it be bridge, chess, or stock selection than to have opponents who have been taught that thinking is a waste of energy?” – Warren Buffett, 1985 Berkshire Hathaway Letter to Shareholders


--------------------------------------


Liked this article? Then you"ll probably like my other missives on


this topic as well. Go here to access them (free, of course).


--------------------------------------

Thursday, March 23, 2017

Eric Mindich's $12 Billion Eton Park Is Returning Capital To Investors: Here Are His Biggest Holdings

Once upon a time Eric Mindich was best known for being the Goldman "wunderkind" - the youngest-ever Goldman partner, who parlayed his reputation into the 2004 launch of his hedge fund Eton Park. Unfortunately for Mindich, after over a decade of running other people"s money, the hedge fund apocalypse caught up with the ex-youngest partner, and after a year of losses, which led to an exodus of investors from Mindich’s $12 billion Eton Park Capital Management, which fell about 11% last year, the hedge fund is now said to be returning capital to investors.


According to Bloomberg, Eric Mindich, whose hedge fund startup in 2004 was among the largest in the industry, is returning client capital after 13 years.


Mindich, 49, plans to return all outside funds in New York-based Eton Park Capital Management because he doesn’t believe he’ll be able to run a global, multi-disciplinary investment firm under current conditions, according to a person with knowledge of the matter.


Readers may recall Eric Mindich for two other notable accomplishments: as we first reported back in September 2009, Mindich was none other than the president of the infamous Plunge Protection Team, as discussed in  "What Is Goldman Alum Eric Mindich"s Role As Chair Of The Asset Managers" Committee Of The President"s Working Group?"


The other notable event involving Mindich was the 2011 report that he was among the hedge fund managers getting direct inside information about the fate of Fannie and Freddie ahead of their bailout, from none other than Hank Paulson, as we discussed in "Hank Paulson Tipped Off The Goldman-Led "Plunge Protection Team" About Fannie Bankruptcy 7 Weeks In Advance."


Paulson... went on to describe a possible scenario for placing Fannie and Freddie into “conservatorship” -- a government seizure designed to allow the firms to continue operations despite heavy losses in the mortgage markets."


The gathering comprised some of Wall Street"s most storied investors. Mindich, a former chief strategy officer of New York- based Goldman Sachs, started Eton Park in 2004 with $3.5 billion, at the time one of the biggest hedge-fund launches ever. [Dinakar] Singh, a former head of Goldman"s proprietary-trading desk, also began his fund in 2004, in partnership with private- equity firm Texas Pacific Group Ltd. Lone Pine"s [Stephen] Mandel worked as a retail analyst at Goldman before joining Julian Robertson"s Tiger Management LLC, one of the most successful hedge funds of the 1980s and 1990s. He started his own firm in 1997. [Daniel] Och was co-head of U.S. equity trading at Goldman before founding Och-Ziff in 1994. The publicly listed firm managed $28.9 billion in November. One other Goldman Sachs alumnus was at the meeting: Frank Brosens, founder and principal of Taconic Capital Advisors LP, who worked at Goldman as an arbitrageur and who was a protege of Robert Rubin, who went on to become Treasury secretary.


In other words the point of the meeting was nothing short of the former Goldman CEO telling all his former Goldman colleagues just what he was planning on doing in his capacity as Treasury Secretary.


In any case, while we await details as to how this formerly high-flying Icarus crashed so low, here are his biggest holdings:


it is worth noting that NXP, MSFT, and BAC - some of Eton Park"s biggest holdings, tumbled on Tuesday, and one wonders if Mindich was the big redemption mentioned earlier this week by Mohamed El-Erian.